TAO climbs 22.1% – September 21, 2026
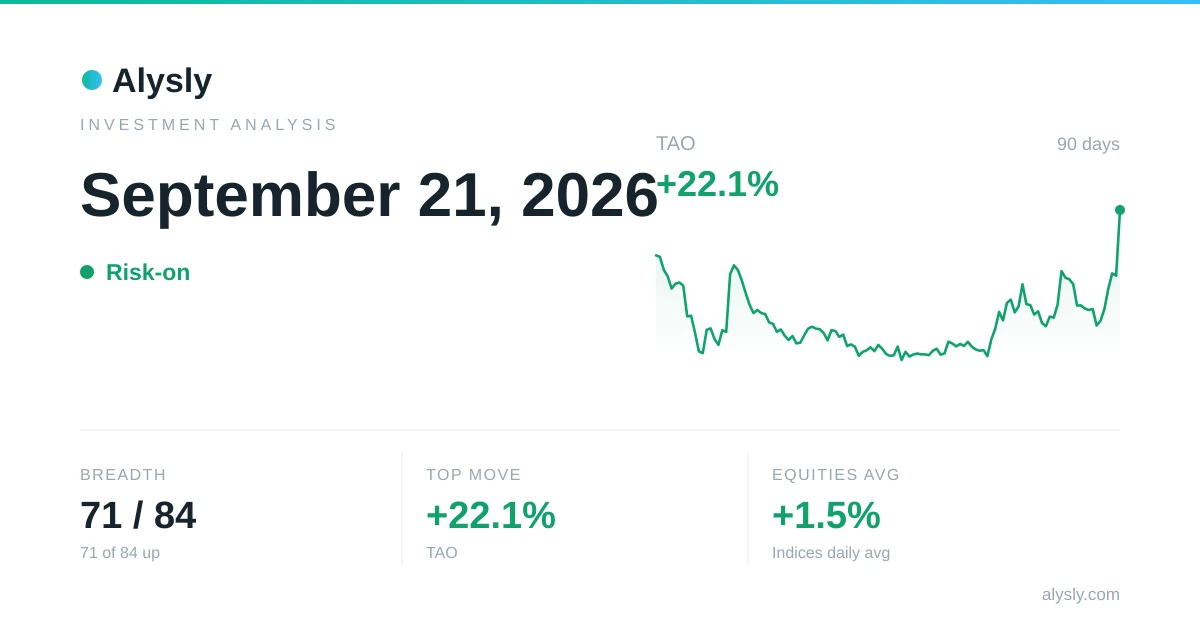
At the close on September 21, 2026, the markets tracked by Alysly showed clear risk-on appetite: 71 of 84 monitored assets (84 %) closed higher. The standout mover was the crypto asset TAO at +22.1 %. The major equity indices moved +1.5 % on average, with crypto around +7.2 %.
The key points at a glance
- Breadth: 71 of 84 assets higher (84 %), clear risk-on appetite.
- Biggest daily move: TAO at +22.1 %.
- Indices: 16 of 17 higher, strongest Nasdaq 100 (+2.77 %), weakest Nikkei 225 (-0.00 %).
- Asset classes: leading crypto (+7.2 %), lagging precious metals (-1.0 %).
- Crypto: top gainer FORM (+36.8 %), top loser XTZ (-2.9 %).
- Correlation: EUR/USD ↔ Gold at +0.53 (moderately correlated).
- Real assets: top hammer price Porsche 911 Turbo (964) · 1991–1994 at $480,964 (Classic cars).
Market barometer
Breadth = share of all tracked instruments (indices, liquid crypto, commodities, forex) with a positive daily change. Bars scale with the magnitude of each asset class's average daily return.
In focus: TAO
At +22.1 %, TAO was the day's most notable single move. The chart shows its trajectory over the selected range:
Indices on the day
Every index we track is listed in the index overview.


Of the 17 benchmark indices tracked, 16 finished the day higher, so the majority advanced. Nasdaq 100 led the field at +2.77 %, while Nikkei 225 trailed at -0.00 %. The “52W” column shows where each index sits within its yearly range. A marker far to the right means it is trading close to its 52-week high.
Crypto: daily gainers & losers
From the 50 largest crypto assets by trading volume, excluding illiquid micro-caps.
Gainers
 FORM
 PHA
 MUBARAK
 TAO
 PEPE
 FET
 XTZ
 ZEC
 ENA
 Avalanche
 XAUT
 USDE
Across liquid coins, crypto came in at +7.2 %. Out in front was FORM at +36.8 %, with XTZ trailing at -2.9 %. Crypto remains the most volatile asset class covered here. Daily swings of this magnitude are normal and say little about the long-term trend.
Commodities & precious metals
All series: commodities and precious metals.
Precious metals averaged -1.0 %, energy and industrial commodities -0.1 %. Both groups declined. Gold is a traditional hedge, while crude oil and copper act as growth barometers.
| Name | Price | Change |
|---|---|---|
| Gold | 4350.2 | -0.92 % |
| Silver | 67.277 | -1.09 % |
| Platinum 18 Sep 2026 | 1806.4 | – |
| Palladium 18 Sep 2026 | 1319.5 | – |
| WTI crude | 67.75 | +0.19 % |
| Brent crude 18 Sep 2026 | 103.87 | – |
| Gasoline | 2.8822 | -0.47 % |
| Heating oil 18 Sep 2026 | 4.8444 | – |
| Copper 18 Sep 2026 | 6.6915 | – |
Foreign exchange (Forex)
All currency pairs are listed in the forex overview.
| Pair | Price | Change |
|---|---|---|
  EUR/USD 18 Sep 2026 | 1.1523 | – |
 GBP/USD 18 Sep 2026 | 1.3396 | – |
 USD/JPY 18 Sep 2026 | 155.654 | – |
 AUD/USD 18 Sep 2026 | 0.71165 | – |
 USD/CAD 18 Sep 2026 | 1.39344 | – |
 USD/CHF 18 Sep 2026 | 0.814034 | – |
Real assets: new hammer prices
Since 14 September 2026, 2 new hammer prices were added. There is no daily close here: trading happens when a lot is called, and only then does a price exist.
| Asset class | Records | Median | Highest hammer price | Price |
|---|---|---|---|---|
| Classic cars | 2 | $302,982 | Porsche 911 Turbo (964) · 1991–1994 15 Sep 2026 | $480,964 |
Median = the middle hammer price among this window's records, not the value of a fixed position. It moves simply because different items come up for sale each week. The price index below avoids exactly this composition effect. Prices are hammer prices including the buyer's premium.
Nothing was sold at auction in trading cards in this window. The last sale on file is 7 days old (14 September 2026). Where trading is rare and expensive, gaps like this belong to the market rather than to a failed fetch. No hammer price was recorded in watches in this window. The latest record stems from 13 June 2026, so 100 days ago. In a thinly traded collectors' market such a pause is normal, not a missing update.
The trading-card price index stands at 587.7, +221.6 % against a year ago (base 100 at the first quarter covered, as of 14 September 2026). It measures price changes of the same good rather than the median of a changing offer. Against the previous reading (29 June 2026) that is +5.2 %, a quarterly figure rather than a daily one.
Residential property: an official index, not a hammer price
For residential property there are no individual sales to report: prices there are formed in statistics, not under the hammer. The latest available reading is 1 June 2026, 112 days before this report. The gap reflects the publication lag of the sources rather than missing data.
| Series | Level | Prior print | 1 year |
|---|---|---|---|
| United States (Case-Shiller) 1 Jun 2026 | 336.7 | +0.4 % | +1.7 % |
| Germany 31 Mar 2026 | 153.4 | +0.3 % | +1.4 % |
| Euro area 31 Mar 2026 | 157.4 | +0.9 % | +4.6 % |
Cross-asset correlations
Over the past 90 trading days, EUR/USD and Gold were moderately correlated, with a correlation coefficient of +0.53. A value near +1 means they move together, near −1 they move opposite, near 0 there is no linear link. For portfolio diversification, low or negative correlations are valuable because they smooth out volatility.
| Pair | r (90d) | −1 … +1 |
|---|---|---|
| S&P 500 ↔ Bitcoin | +0.35 | |
| S&P 500 ↔ Gold | +0.40 | |
| Gold ↔ Crude oil (WTI) | -0.20 | |
| EUR/USD ↔ Gold | +0.53 |
Summary
Overall, September 21, 2026 was a day of clear risk-on appetite across the markets Alysly tracks: 71 of 84 assets gained. The headline came from TAO at +22.1 %. Across asset classes, crypto led (+7.2 %) while precious metals lagged (-1.0 %). The correlation between EUR/USD and Gold stood at +0.53, a gauge of how much diversification benefit combining the two currently offers. Away from the capital markets, the top hammer price was Porsche 911 Turbo (964) · 1991–1994 at $480,964, a price struck at a single table rather than on an exchange. A single trading day is only a small slice, though: over longer periods, asset classes, regions and holding period shape a portfolio's result more than any one day's move.
Latest Investment Analysis
 · Mixed
Crypto, commodities & FX this week: Arbitrum +66.3% · September 14–18, 2026
 · Mixed
The week in markets: Euro STOXX 50 weighs on the week (-2.2%) · September 14–18, 2026
 · Mixed
Arbitrum climbs 24.8% – September 18, 2026
 · Risk-on
NEAR is the day's top gainer, up 20.1% – September 17, 2026
 · Mixed
NEAR surges 12.2% – September 16, 2026