Level 0 Investing & ETF Basics · Part 9/16
ETFs & Tax in Germany: The Essentials
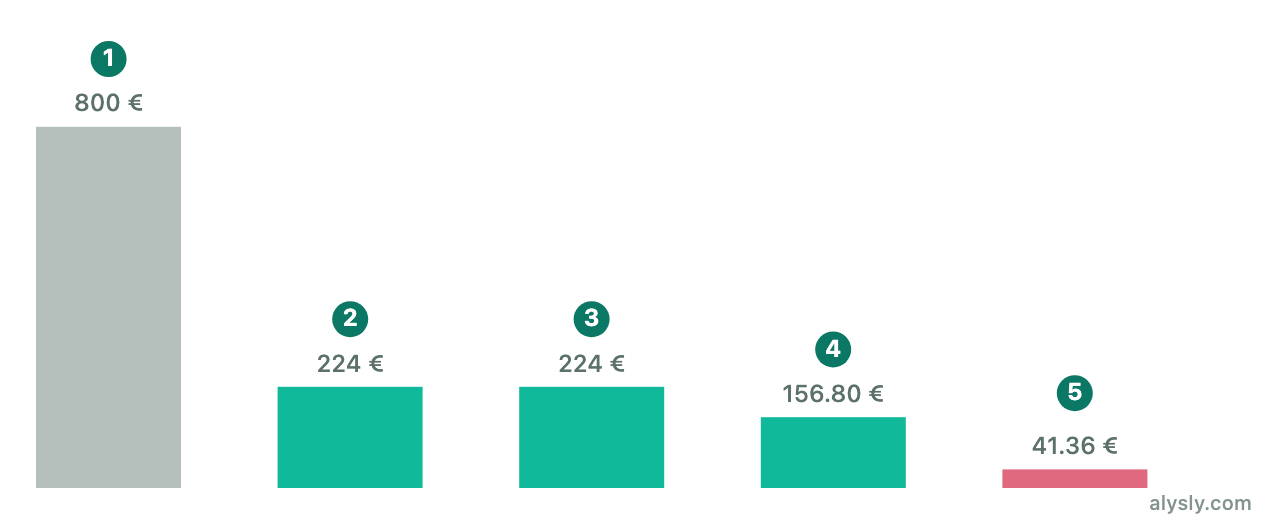
In Germany, ETF gains are subject to the flat capital gains tax (25% plus solidarity surcharge and possibly church tax). Three terms determine how much of it is actually due.
1. Saver’s Allowance (Sparerpauschbetrag)
Each year €1,000 of capital income is tax-free (jointly assessed couples: €2,000). It is applied automatically when an exemption order (Freistellungsauftrag) is on file with the broker.
2. Partial Exemption (Teilfreistellung)
For equity funds (at least 51% stocks), 30% of income is tax-free. This offsets taxes already paid at fund level and lowers the effective tax on equity-ETF gains.
3. Advance Lump-Sum Tax (Vorabpauschale)
Because accumulating ETFs pay no dividends, the Vorabpauschale applies. This yearly advance tax on a notional minimum return makes sure that accumulating funds are taxed on an ongoing basis too.
- It only applies if the fund rose during the year.
- It is usually small and credited against tax on a later sale (no double taxation).
- German brokers collect it automatically from the cash account.
Holding via a Foreign Broker
Foreign brokers do not withhold German tax. The income must then be declared in the tax return; with a German broker the deduction happens automatically.
This article is general information, not tax advice. Rules can change.